When faced with an unexpected medical situation, deciding where to seek treatment can significantly impact your finances. Understanding the difference in costs between urgent care and the emergency room (ER) is essential, especially when navigating the complexities of insurance coverage. This guide provides practical advice on how to effectively manage and potentially reduce these costs.
Understanding the Differences between Urgent Care and ER
Urgent care centers and emergency rooms both serve essential roles in the healthcare system, but they cater to different levels of medical need. Urgent care is typically best for non-life-threatening conditions such as minor fractures, sprains, and common infections. These centers are usually open during extended hours, including weekends, and offer a more affordable alternative to the ER for such issues.
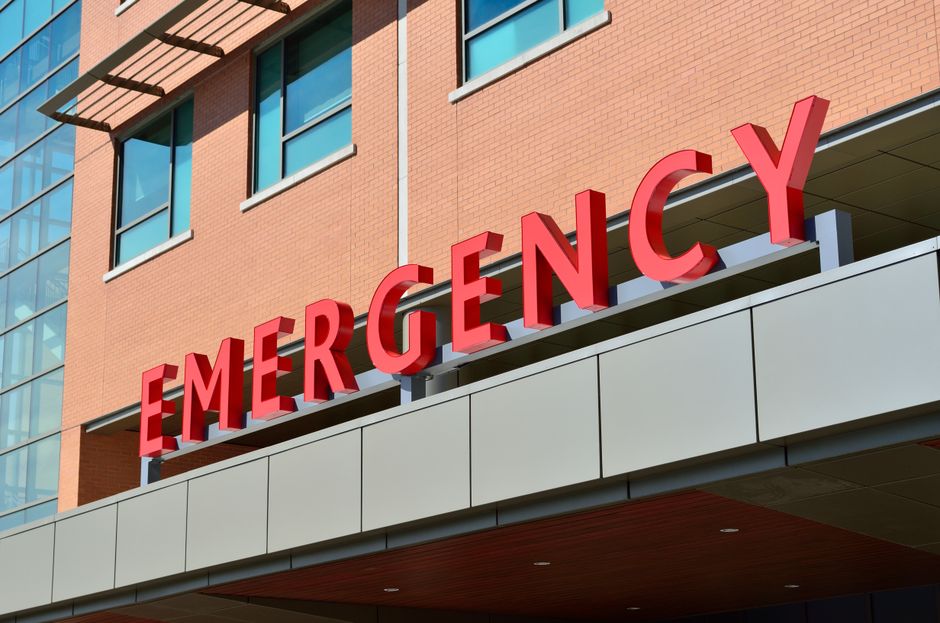
The ER, on the other hand, is designed to handle severe and life-threatening conditions such as chest pain, severe bleeding, or head injuries. With its advanced medical equipment and specialized staff available 24/7, ER services come with higher costs. This distinction is crucial when determining where to seek care, as it directly affects your out-of-pocket expenses.
How Insurance Coverage Impacts Costs
Insurance plans vary significantly, influencing how much you will pay for urgent care vs. an ER visit. Most plans cover both, but the co-pays and deductibles can differ. Typically, urgent care visits have lower co-pays compared to ER visits, since the latter involves more complex and costly resources.
Moreover, some insurance policies might require higher deductibles for ER services. It’s important to check your specific plan details to understand these differences. Knowing what your insurance covers can prevent unexpected bills and ensure you choose the most cost-effective care option.
Strategies to Lower Your Medical Costs
Choose the Right Care for Your Condition
One of the most effective ways to manage costs is by accurately assessing the severity of your condition. For non-emergencies, opt for urgent care to benefit from lower costs. Keep in mind that if you’re unsure about the severity, many urgent care centers offer guidance on whether your situation warrants an ER visit.
Utilize Telehealth Services
Telehealth has become a popular and cost-effective tool for managing minor medical issues. Many insurance plans cover telehealth visits, which can help you avoid unnecessary trips to both urgent care and the ER. Through virtual consultations, you can quickly determine the appropriate level of care needed.
Understand Your Plan’s Network
Staying within your insurance network is crucial to minimizing expenses. Out-of-network visits often come with higher out-of-pocket costs. Familiarize yourself with the urgent care centers and hospitals in your network before you need them, ensuring that you can make informed and cost-effective decisions when emergencies arise.
Negotiating Medical Bills
Even with insurance, medical bills can be daunting. If you receive a high bill from an ER visit, know that negotiation is possible. Contact the billing department to discuss payment plans or possible discounts based on financial hardship. Hospitals often have financial assistance programs to help patients manage unexpected expenses.
Common Mistakes to Avoid
- Ignoring Insurance Details: Failing to understand your plan’s details can lead to avoidable costs. Always review your coverage specifics.
- Visiting the ER for Non-Emergencies: This can lead to unnecessary expenses. When in doubt, start with urgent care.
- Overlooking Telehealth Options: This can be a convenient and less costly first step for non-urgent issues.
Conclusion: Taking Control of Your Healthcare Costs
Understanding the financial implications of choosing between urgent care and the ER is crucial in managing your healthcare costs. By being informed and proactive about your insurance coverage and healthcare choices, you can make decisions that prioritize both your health and your finances. Remember, when in doubt, consulting with your healthcare provider or insurance company can provide additional guidance tailored to your specific situation.